Flexible Working Capital for Changing Business Needs

Revolving Credit Facilities for UK Businesses
▬ Revolving Credit Facilities for UK Businesses ▬

Access Working Capital When You Need It

Cash-flow needs rarely arrive in neat monthly cycles. A delayed customer payment, supplier deadline, VAT bill or seasonal stock purchase can create pressure even when the business is profitable.

A revolving credit facility gives an eligible business access to an agreed limit. The business can draw what it needs, repay it and potentially draw again during the facility term, subject to the agreement and continued availability.

TMS Finance reviews the purpose, bank activity, turnover, existing borrowing and repayment route before approaching suitable providers from our selected panel.

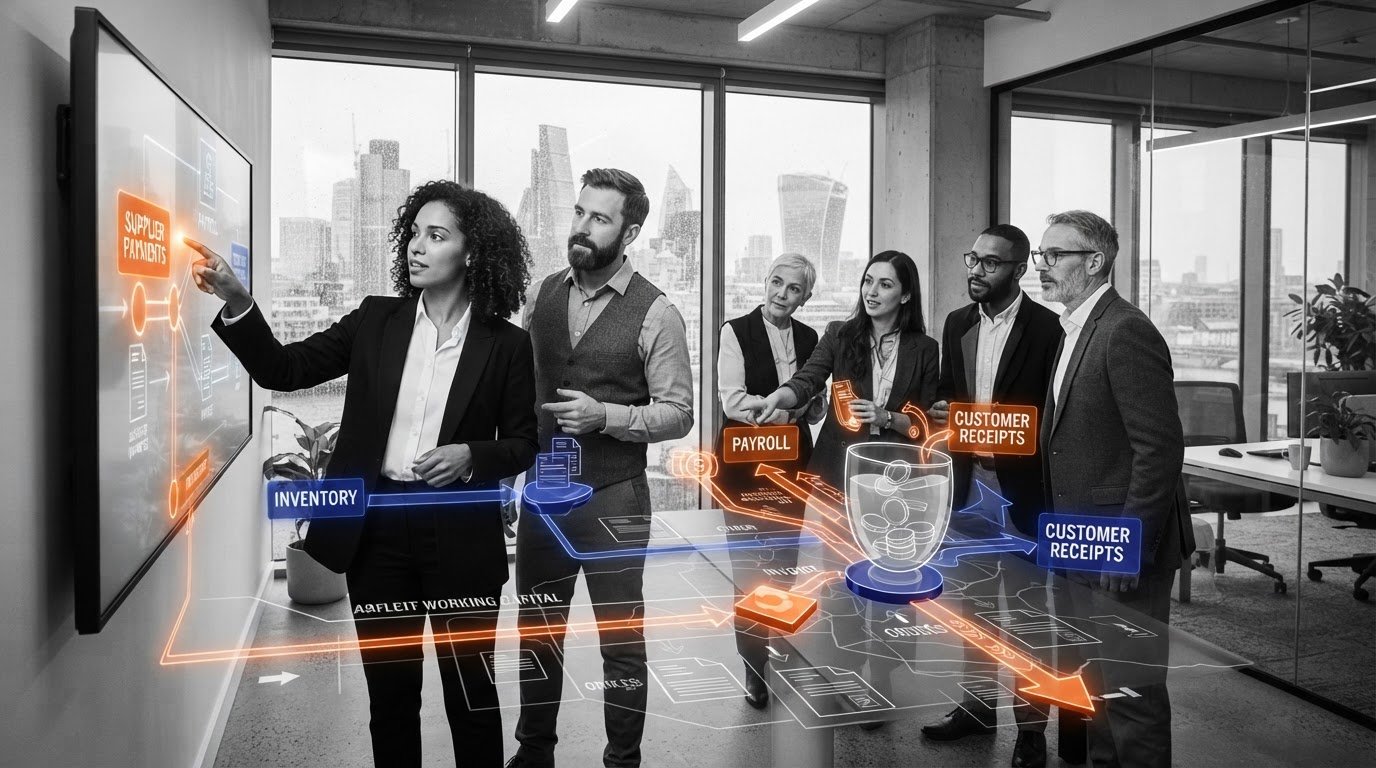
Facilities may support short-term working-capital needs including supplier payments, stock, VAT, payroll, project costs and seasonal demand.

Submitting an enquiry does not commit you to proceed. Finance is subject to status, affordability, provider criteria and approval. Fees, security or personal guarantees may apply.

▬ What Can a Revolving Credit Facility Support? ▬

Use the facility for short-term costs that have a clear repayment route.

A revolving credit facility can support changing cash-flow needs without a new application for every drawdown, subject to the provider’s terms.

Common uses include:

Flexibility Only Helps If the Facility Fits

A revolving facility can reduce the need to reapply whenever a short-term cash-flow gap appears. But flexibility does not make poor borrowing affordable.

Compare the total cost, drawdown process, fees, repayment mechanics, renewal terms and any clean-down requirement. A revolving facility may not suit long-term fixed investment or a business repeatedly borrowing to cover ongoing losses.

Depending on the purpose, a term loan, asset finance, invoice finance or merchant cash advance may provide a better structure. TMS Finance reviews the requirement before recommending a route.

Compare the Main Working-Capital Routes

Common Working-Capital Structures

RCF 1
Revolving Credit Facility

Access an agreed credit limit, draw what the business needs, repay it and potentially draw again during the facility term. Interest is usually charged on the amount used, although arrangement, renewal, non-utilisation or transaction fees may also apply.

RCF 2
Business Overdraft

Bank-account-linked working capital that can support day-to-day cash flow. Availability and pricing depend on the bank, account conduct and review terms. Limits can be reduced or withdrawn, so renewal terms matter.

RCF3
Short-Term Business Loan

A fixed amount repaid over an agreed term. This may suit a defined cost with a clear repayment plan, but the available balance does not automatically replenish as repayments are made.

How TMS Finance Helps

TMS Finance reviews the purpose, current borrowing, bank activity and repayment route. We compare realistic structures from selected providers, explain the limit, interest, fees, security and renewal terms, and stay involved through application and completion.

How a Revolving Credit Facility Works

A clear process from cash-flow requirement to an active facility.

1

Send Us the Cash-Flow Requirement

Provide the amount, purpose, timescale, turnover, recent bank statements, existing borrowing and the expected repayment source.

2

We Assess Facility Fit

We review the usage pattern, affordability and current commitments, then consider whether a revolving facility, overdraft, term loan or another route better matches the requirement.

3

Review Terms and Activate

We explain the limit, drawdown process, interest, fees, security, term, renewal and repayment mechanics. If approved and accepted, the facility can be activated.

▬ What Providers Usually Need ▬

Information We Need

Requirements vary by provider and requested limit. Complete information prevents avoidable delays.

Revolving Credit Facility FAQs

Clear answers before you consider a flexible credit line.

It is a reusable credit line up to an agreed limit. The business can draw funds, repay them and potentially draw again during the facility term, subject to the agreement and continued availability.

Interest is commonly charged on the amount drawn rather than the whole approved limit, but providers may also charge arrangement, renewal, non-utilisation, transaction or other fees. Check the complete cost before proceeding.

An overdraft is normally attached to the business bank account. A revolving credit facility may be provided separately and can have different drawdown, repayment and review arrangements. Availability, pricing and security vary.

The limit depends on turnover, cash flow, bank activity, trading history, credit profile, existing borrowing, purpose and the provider’s assessment. It should not be estimated from turnover alone.

Some providers may allow refinancing, but a new facility should improve the structure rather than simply add another expensive layer. TMS Finance will review the current commitments first.

Requirements vary. A provider may request a personal guarantee, debenture or other security. The exact position should be understood before signing.

A clear request with complete accounts, bank statements and borrowing information can be assessed more quickly. Timing depends on the provider, requested limit and any security or due diligence required.

Need Working Capital Without Reapplying Every Time?

Tell us the limit you need, what the funds will support, when you expect to draw them and how the balance will be repaid. TMS Finance will review whether a revolving facility or another funding route is more suitable.

▬ KNOWLEDGE HUB ▬

Industry Insights

Discover expert finance insights, tips, and updates to help your business thrive with TMS Finance.