Bank said no to your business loan? Here’s what next
Being turned down by a high street bank does not mean your business is unfundable. Most rejections come down to rigid, one-size-fits-all criteria rather than
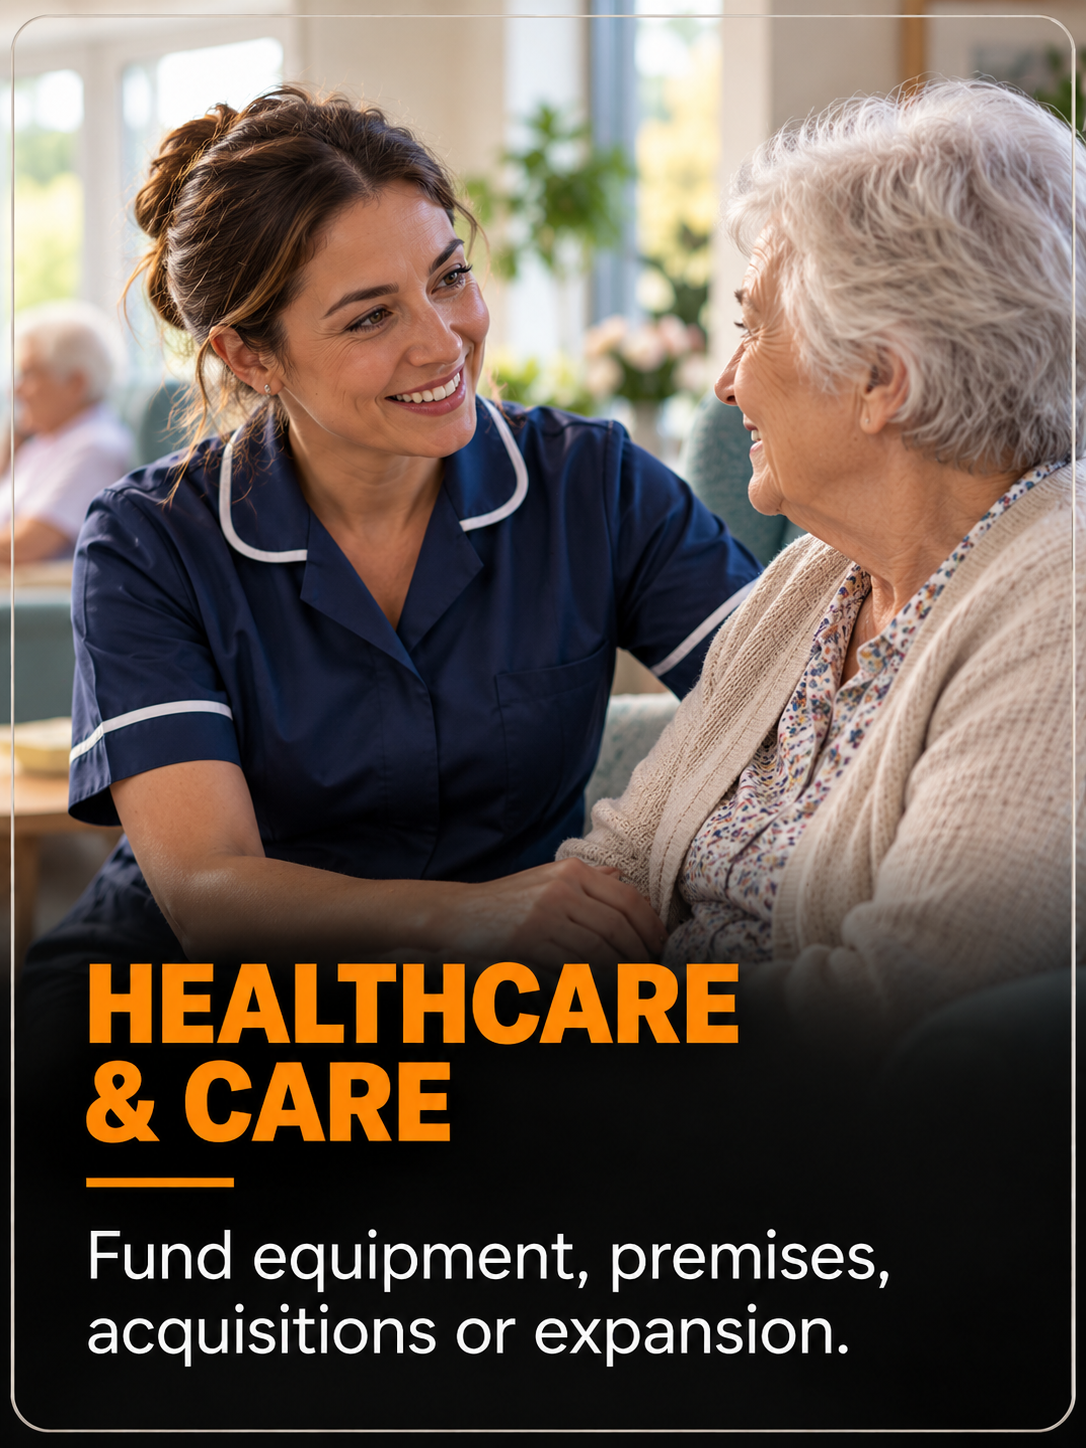
Care providers and healthcare businesses face recurring payroll, compliance, equipment and premises costs, while payments from private clients, local authorities or other organisations may arrive later.
Commercial finance can help manage these timing gaps, fund essential assets or support an acquisition, refurbishment or new service.
TMS Finance reviews the provider's trading history, payment sources, occupancy or utilisation, staffing model, regulatory position and intended use of funds before approaching suitable lenders.
Funding may be available for staffing, equipment, vehicles, premises, acquisitions, refurbishments and working capital.
Submitting an enquiry does not commit you to proceed. Finance is subject to status, affordability, lender criteria, due diligence and approval.
Funding for People, Premises and Essential Services
Finance can help established providers invest in safe, efficient delivery while managing the gap between operating costs and incoming payments.
Common requirements include:
Depending on your business and funding requirement, we may be able to help with:
Start your finance enquiry
Complete the form and a member of the TMS Finance team will contact you to discuss your enquiry.
Trusted by UK Businesses.
We review trading performance, payment sources, occupancy or utilisation, staffing costs, regulatory position and the proposed use of funds. Potential routes may include business loans, invoice finance, asset finance, property finance or equity finance. Lenders make their own clinical-sector, credit and affordability assessments.
Here are some of the main questions that businesses in this sector ask.
Potential applicants include established care homes, domiciliary care providers, clinics, pharmacies, dental practices and other eligible healthcare businesses. Lender appetite and regulatory requirements vary by sector.
Working-capital facilities may help bridge timing gaps where payments are delayed, provided the business can demonstrate a sustainable route to repayment. Funding should not replace an underlying need to correct persistent losses.
Asset finance may be suitable for qualifying clinical, mobility, care, technology and specialist transport equipment. The asset, supplier, useful life and regulatory suitability will be considered.
Acquisition funding may be available where the buyer, target, regulatory position, valuation and cash contribution meet lender criteria. Detailed due diligence and professional advice are normally required.
Lenders may review registration, inspection outcomes, action plans and management experience. Material regulatory concerns can limit options, so accurate and current information is essential.
Invoice finance may be possible for eligible business or public-sector receivables. The contract, payer, invoice terms, concentration and whether the service has been accepted will influence availability.
Common requirements include accounts, bank statements, management information, occupancy or utilisation data, payment-source details, regulatory information, existing debt and a clear breakdown of the funding requirement.
Tell us about the service, funding purpose, trading performance, payment cycle and timescale. We will review the requirement and explain the routes that may be available.
Read practical guides on equipment, acquisition, property and working-capital finance for UK healthcare and care businesses.

Being turned down by a high street bank does not mean your business is unfundable. Most rejections come down to rigid, one-size-fits-all criteria rather than

A generous headline loan figure means nothing if cash flow dries up before practical completion. For UK developers, sourcing property development…
Relying on a single retail bank loan to purchase an established trading company is often a direct route to a broken transaction. Securing dependable…
Over 52% of UK business-to-business invoices are now paid past their agreed terms, contributing to an annual £11 billion drain on the national…
Paying a commercial landlord every month often feels like funding someone else’s retirement while your own cash flow remains under constant pressure….
A low headline interest rate can be the most expensive mistake a developer makes if they overlook how exit fees are calculated. You likely understand…